By Anderson Pavanello | Meu Contador Online
Research cut-off: September 22, 2026
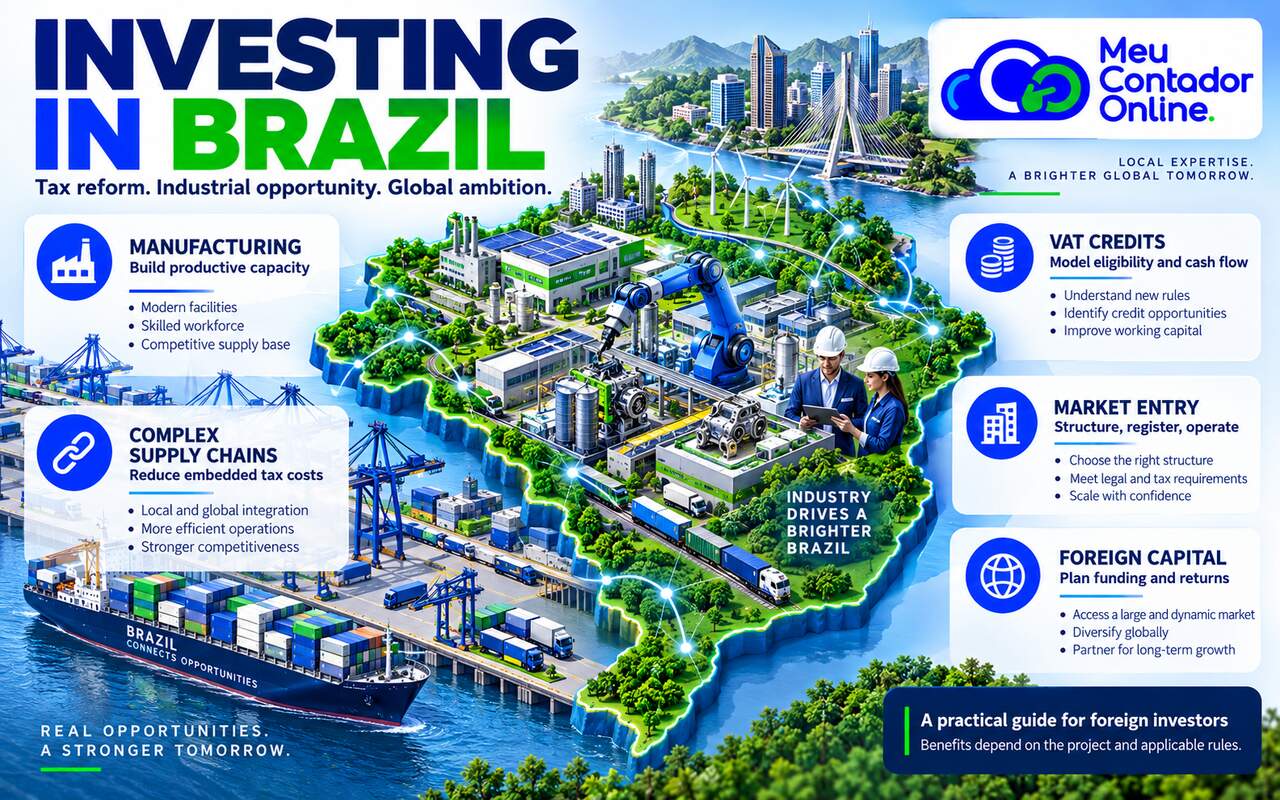
Brazil deserves a prominent place on the shortlist of companies
planning their next international investment. For manufacturers,
technology providers and businesses building sophisticated supply
chains, the consumption tax reform creates a compelling reason to
reassess the country’s potential.
The opportunity is particularly relevant to investors whose products
move through several stages of production. A tax system that allows
eligible business inputs to generate recoverable credits can reduce
taxes embedded in production costs, improve the economics of
specialization and make investment decisions more closely reflect
operational efficiency.
Our recommendation is to begin evaluating Brazil now. Use the
transition to identify customers, qualify suppliers, compare locations
and build an investment model. A project with sound commercial
fundamentals should not be dismissed on the basis of tax assumptions
inherited from the old system.
This guide explains the investment case, the practical implications
for industrial projects and the steps foreign investors should take
before committing capital. Its focus is direct business investment,
rather than personal securities portfolios or residential property
purchases.
Why
does Brazil’s tax reform matter to foreign investors?
Brazil is implementing a dual value-added tax system: the federal
CBS and the state and municipal IBS.
The reform aims to reduce cascading taxation and move consumption
taxation toward the destination of consumption. A separate
Selective Tax, or IS, applies to specified goods and
services. These changes can improve the framework within which
businesses invest, produce and trade. Source:
Receita Federal’s reform overview.
For a foreign investment committee, the strategic question is how
these changes affect the project’s cash flows: which costs become
creditable, when credits can be used, what customers will pay and how
much working capital the business needs.
The international policy assessment supports taking the reform
seriously. In its 2026 consultation with Brazil, the IMF identified
continued implementation of the VAT reform, alongside improvements in
the business environment and other reforms, as a way to support
productivity and medium-term growth. That is support for the reform’s
direction, rather than a forecast of returns for any individual
investor. Source:
IMF, 2026 Article IV consultation.
Will
the reform favor industrialization and complex supply chains?
It can materially improve their tax economics, particularly
where unrecoverable taxes currently accumulate through
production. The investment opportunity is strongest when a
project can translate better credit recovery into competitive pricing,
stronger margins or more productive capital allocation.
Consider a manufacturer that purchases engineered components,
tooling, maintenance, logistics and specialist services. Its
competitiveness depends on the combined cost of an entire production
network. If taxes on eligible purchases can be recovered effectively,
each additional productive stage need not add another layer of
unrecoverable consumption tax.
The IBS regulations provide for credits under the regular regime,
subject to legal conditions, and address exports and capital goods.
Eligibility, documentation and the rules governing settlement of the
associated tax matter: receiving an invoice does not automatically make
every amount an immediately usable credit. Source:
CGIBS Resolution No. 6/2026, particularly the credit provisions.
Our investment interpretation is that this can support industrial
development through three channels:
- More efficient specialization. A manufacturer can
assess an outside supplier on quality, productivity and total
recoverable cost, with less distortion from taxes accumulated between
businesses. - A stronger case for sophisticated production.
Products requiring multiple suppliers and transformation stages can
benefit when embedded taxes are removed from eligible inputs. - Better capital allocation. Comparing production
sites, outsourcing arrangements and equipment purchases becomes more
meaningful when recoverable taxes are separated from permanent
costs.
The relevant Portuguese term is desoneração da cadeia
produtiva: relief from taxes embedded in the production chain. It
does not mean that complex products become universally
tax-exempt. Nor does it establish a blanket reduction in every
manufacturer’s total tax bill.
The size of the benefit depends on the existing tax position,
suppliers, purchases, selling prices and credit recovery. A company that
already recovers most input taxes may experience a different result from
one carrying substantial unrecoverable costs.
A simple
illustration of how VAT credits work
The following is an original teaching example, not a calculation of
Brazilian tax liability. Assume a hypothetical VAT rate of
10%, three fully taxable businesses, immediately
available eligible credits, and no other purchases or special rules.
Amounts are in arbitrary currency units.
| Production stage | Sale before VAT | VAT charged | Input VAT credit | Net VAT remitted |
|---|---|---|---|---|
| Materials supplier | 100 | 10 | 0 | 10 |
| Component manufacturer | 160 | 16 | 10 | 6 |
| Finished-product manufacturer | 250 | 25 | 16 | 9 |
| Total tax remitted across the chain | — | — | — | 25 |
The last invoice totals 275, including 25 of VAT. The amounts charged
on successive invoices do not all become separate permanent tax costs:
credits offset tax already charged upstream. If the last buyer is
another eligible business, it may continue the credit chain; a final
consumer generally bears the tax.
The 10% assumption is not Brazil’s official CBS/IBS
rate. This example demonstrates the credit mechanism only. It
does not quantify savings against Brazil’s previous system, which
already includes credit mechanisms with different rules and
limitations.
Where
should industrial investors look for opportunities?
Use the reform as a reason to investigate productive opportunities,
then validate each one commercially. The following are investment
hypotheses for screening, rather than official forecasts of winning
sectors.
| Opportunity to investigate | Why it fits the investment thesis | Evidence to obtain before investing |
|---|---|---|
| Industrial machinery and automation | Productivity improvements can support local manufacturing competitiveness | Customer order pipeline, service coverage and equipment economics |
| Precision components and industrial assemblies | Multiple production stages make the treatment of purchased inputs particularly relevant | Supplier quality, engineering capability and product-level margins |
| Food processing and agricultural equipment | Investment can connect production, processing, storage and distribution | Raw-material security, logistics costs and customer demand |
| Energy equipment and electrical systems | Local assembly and specialist suppliers may support large project requirements | Procurement commitments, certification and installation capacity |
| Medical and laboratory equipment | Technical production and after-sales support may create a differentiated local proposition | Regulatory pathway, purchasing cycles and maintenance requirements |
Start with a narrow commercial question: Which customer need
can our Brazilian operation serve better than the available
alternatives? A clear answer is a stronger foundation than a
tax incentive alone.
For an overseas manufacturer, a sensible progression might be
distribution and technical support, followed by local assembly, and then
deeper localization once volume and supplier quality justify it. Other
projects may warrant a factory from the outset. The choice should follow
demand, economics and execution capability.
When does the tax reform
take effect?
The transition matters because a factory planned today may begin
operating under one set of rules and reach capacity under another.
| Period | Principal consumption-tax milestone |
|---|---|
| 2026 | CBS and IBS testing; specific compliance and collection arrangements apply |
| 2027–2028 | CBS replaces PIS/Cofins; IBS remains at its initial transitional level; the Selective Tax begins in 2027; IPI rates become zero for most products, with exceptions protecting the Manaus Free Trade Zone |
| 2029–2032 | Gradual transition from ICMS and ISS to IBS |
| 2033 | Full operation of the new consumption-tax model; ICMS and ISS end |
Source:
Receita Federal’s official transition schedule.
Prepare separate financial views for construction, commissioning,
early operation and mature operation. A single tax assumption applied to
every forecast year can hide both transition costs and future
benefits.
How
should investors model equipment purchases and exports?
For a capital-intensive project, distinguish the equipment’s
underlying price from taxes that are recoverable, taxes that remain a
cost, and financing needed while recoverable amounts remain
outstanding.
Ask the project team to prepare an equipment schedule showing
purchase date, supplier, import content, tax treatment, documentation
and expected recovery date. A credit worth 100 on paper has a different
financing impact if it is usable promptly or remains outstanding for an
extended period.
Export projects should similarly model the treatment of foreign sales
alongside the recovery of input taxes. The intended competitive benefit
depends partly on turning eligible credits into usable economic value.
Export treatment and capital-goods provisions must be checked against
the project’s actual transactions. Source:
CGIBS’s IBS regulations, export and capital-goods provisions.
Use at least three recovery scenarios: expected timing, delayed
recovery and a stressed case with some disputed credits. This gives the
investment committee a practical range for liquidity requirements.
For imported machinery, obtain a full landed-cost quotation. Keep
customs charges, freight, insurance, clearance, installation and tax
recovery assumptions visible as separate items. Do not treat the VAT
reform as an automatic waiver of import duties.
What is the
best way to enter the Brazilian market?
Choose an entry route that matches how much control, capital and
operational responsibility the business needs.
| Entry route | Useful when | Main diligence focus |
|---|---|---|
| Local distributor or commercial partner | Testing demand before substantial fixed investment | Customer access, exclusivity, pricing and termination rights |
| New Brazilian subsidiary | Building a controlled local operation | Incorporation, funding, staffing, tax setup and licensing |
| Acquisition | Seeking an existing team, assets or customer base | Historical liabilities, quality of earnings and integration |
| Joint venture | Combining technology or capital with local capabilities | Governance, contributions, information rights and exit arrangements |
Common corporate forms include the Sociedade Limitada, or
Ltda., and the Sociedade Anônima, or S.A.
Their governance and capital structures differ. Select the form around
ownership, financing and decision-making needs. Source:
DREI’s guidance on legal entities.
A foreign-owned Brazilian subsidiary and a branch of an overseas
company are different structures. Have counsel compare the applicable
authorization and registration requirements before choosing between
them.
Can a foreign
investor own a Brazilian company?
Foreign investment is possible across many Brazilian business
activities, including structures with full foreign ownership.
Restrictions and special authorizations can apply depending on the
sector, assets and transaction. A Brazilian partner should therefore be
a commercial or legal decision specific to the project, rather than an
assumed universal requirement. Begin the sector review with the
government’s foreign
investment information portal.
Keep ownership, management and immigration separate. Share ownership
does not by itself establish permission to live or work in Brazil. If
executives will relocate, review their immigration position
independently; Brazil’s investment visa route involves its own process.
Source:
Ministry of Foreign Affairs, investment visa guidance.
What should
be prepared before opening the company?
Build a coordinated incorporation and operating-readiness checklist
with local advisers. Confirm which items apply to the proposed entity
and activity:
- Ownership documents: investor identification,
corporate records, ownership chart and beneficial-owner
information. - Document formalities: legalization or apostille,
translations, powers of attorney and representation requirements. - Corporate design: business activities, registered
address, capital, ownership percentages, administrators and approval
powers. - Registrations: commercial registration, applicable
CPF/CNPJ registrations, tax registrations and digital access. - Banking: account-opening documents, source-of-funds
evidence, authorized signatories and payment controls. - Operating permissions: location, environmental,
fire-safety, product and sector requirements as applicable. - Business systems: accounting, invoicing, inventory,
payroll, purchasing and reporting to the overseas parent.
Use this as a coordination list, not a claim that every item applies
identically to every investor. Registration procedures depend on the
structure and location. The government’s company-opening
portal provides a starting point for the formal process.
Before signing a long lease or ordering machinery, confirm that the
site can support the intended activity. A registered company without the
required operating permissions is not a production-ready business.
How should foreign
capital enter Brazil?
Decide whether funding will take the form of equity, debt or a
combination, then align corporate documentation, banking instructions
and accounting records before transferring funds.
Brazil uses SCE-IED for applicable foreign direct
investment information reporting. Obligations depend on the relevant
transaction and reporting criteria; periodic reporting includes
asset-based thresholds. Avoid assuming that every company has the same
filing schedule or relying on older guides that refer only to previous
systems. Source:
Central Bank’s SCE-IED service guidance.
For each funding movement, record its commercial purpose, authorizing
documents, currency, exchange information and accounting treatment.
Assign responsibility for monitoring reporting obligations and
preserving the evidence.
A useful treasury policy also defines how much currency exposure the
Brazilian operation may carry and who can approve hedging or additional
funding. Model both the operating business in Brazilian reais and the
investor’s return in its reporting currency.
Which taxes
remain relevant beyond CBS and IBS?
The consumption-tax reform is one part of an investment model.
Request a tax memorandum covering corporate income taxes, payroll,
imports, financing, related-party transactions, distributions and
exit.
Keep IRPJ and CSLL, Brazil’s
corporate profit taxes, separate from the consumption-tax analysis. Ask
which profit-tax regime is legally available and how it performs under
the project’s expected margins and expenses. Evaluate eligibility before
comparing numbers.
Can a
foreign-owned company use Simples Nacional?
Do not assume that a small foreign-owned company qualifies for
Simples Nacional. Ownership by a legal entity and having a shareholder
domiciled abroad are important exclusion grounds. Foreign nationality
alone is a different question from foreign domicile. The actual
ownership structure must be checked. Source:
Receita Federal’s Simples Nacional exclusion manual.
For an overseas corporate group establishing a subsidiary, a business
plan based on simplified small-business tax rates can therefore be
inappropriate from the start.
Can profits be remitted
overseas?
Plan distributions using current rules. From January 2026,
Brazilian law generally imposes 10% withholding income tax on profits or
dividends paid, credited, delivered, employed or remitted
abroad. Specific exceptions and transitional provisions exist,
and the law also provides a credit mechanism in qualifying
circumstances. Do not assume an older statement that Brazilian dividends
are universally tax-free remains valid. Source:
Law No. 15,270/2025, Article 3, amending Articles 10 and 10-A of Law
No. 9,249/1995, and Article 8.
For the return model, have advisers confirm the recipient’s status,
any applicable treaty, Brazilian withholding, home-country taxation and
available relief. Treat dividends, loan repayments, interest, service
payments and capital reductions as distinct transactions requiring their
own analysis.
How
should investors compare locations and incentives?
Compare locations using a complete operating model: customer
proximity, freight, ports, power, water, workforce, supplier depth,
property and permitting.
For every incentive offered, ask for the legal basis, eligibility
conditions, duration, reporting requirements and consequences of
noncompliance. Model what happens when it expires or changes during the
reform transition.
Our recommendation is to rank locations twice: first on sustainable
operating economics, then with verified incentives included. A location
that performs well in both comparisons offers a stronger investment case
than one that depends entirely on an untested incentive assumption.
What
should an investment committee require before approval?
Ask for a decision package that connects the reform’s opportunities
to measurable commercial assumptions.
| Workstream | Evidence for the investment decision |
|---|---|
| Demand | Customer interviews, purchase intentions and a realistic sales ramp |
| Production | Capacity plan, quality requirements, supplier quotations and local-content assumptions |
| Tax | Transaction-level treatment, credit eligibility and transition-year calculations |
| Cash | Monthly funding needs, credit-recovery timing and currency sensitivity |
| Legal and regulatory | Ownership review, permissions, contracts and transaction conditions |
| People | Management plan, recruitment costs and training requirements |
| Returns | Operating cash flow, distributions, reinvestment and exit assumptions |
For an acquisition, add historical tax, labor, environmental and
litigation diligence. Reconcile reported earnings with cash generation
and inspect the documentation supporting material tax assets. Attractive
future rules do not resolve historical liabilities.
For a new plant, make land commitments, construction and equipment
orders conditional on the necessary technical and regulatory milestones
wherever commercially feasible.
A practical
roadmap from opportunity to operation
Step 1: Define the
investment thesis
Specify target customers, products, required capabilities and the
reason to operate in Brazil. Decide whether the project primarily serves
domestic demand, exports or both.
Step 2:
Build the commercial and tax model together
Collect expected sales, customer types, supplier quotations, imported
inputs, payroll, capital expenditure and financing assumptions. Model
eligible credits and permanent tax costs separately.
Step 3: Select
the entry structure and location
Compare distribution, incorporation, acquisition and partnership
options. Review ownership, governance and the permissions needed to
operate.
Step 4:
Establish funding and implementation controls
Align capital documentation, banking, foreign-investment reporting,
accounting and approval responsibilities. Build a funding buffer tied to
identifiable risks such as commissioning delays and slower credit
recovery.
Step 5: Test
the operating process before launch
Run sample purchases, invoices, inventory movements, payroll and
management reports through the intended systems. Confirm that commercial
quotations and tax configurations use consistent assumptions.
Step
6: Review actual performance against the investment case
Track margins, tax credits, cash collection, funding and supplier
performance. Update the model as transition rules take effect and
operating evidence replaces initial assumptions.
Frequently
asked questions about investing in Brazil
Is Brazil’s
tax reform a good reason to invest now?
It is a strong reason to reassess opportunities and begin
preparation. The reform can improve the economics of productive
investment, but the final decision should be supported by customer
demand, execution capability and project-level cash flows.
Will complex
manufactured products become tax-free?
No. The investment thesis concerns reducing unrecoverable taxes
accumulated through eligible production inputs. The finished product’s
tax treatment still depends on the applicable rules.
Does a
longer supply chain automatically mean larger savings?
No. The relevant question is how much unrecoverable tax the project
currently carries and how that changes. Count the economic costs and
eligible credits, rather than simply counting suppliers.
What is the best
tax rate to use in a forecast?
Use rates and rules applicable to the forecast year, product and
transaction, with clearly labeled scenarios where an assumption remains
uncertain. A headline estimated standard rate is not a substitute for a
transaction-level calculation.
Should manufacturers wait
until 2033?
Our view is that investors should begin diligence and market
development earlier. Supplier qualification, customer relationships,
site selection and industrial commissioning take time. Stage commitments
around evidence and milestones instead of postponing all preparation
until the transition ends.
What
should I bring to a first meeting with a Brazilian accountant?
Bring the ownership chart, proposed activities, expected revenue,
target customers, principal purchases, import and export plans, payroll
estimates, capital expenditure and funding structure. These allow a
useful discussion of options and costs.
What is the
most common modeling mistake to avoid?
Treating every tax shown on a purchase invoice as either permanently
lost or immediately recoverable. Build a model that distinguishes
eligibility, recognition, use and cash recovery.
Turn
Brazil’s reform into a concrete investment plan
Brazil’s tax reform strengthens the case for looking seriously at
local manufacturing and more sophisticated production networks. For
investors able to combine technology, operating expertise and
disciplined execution, this is an opportunity to build productive
capacity while the country modernizes the way it taxes consumption.
Put Brazil on your investment agenda. Identify the customer
opportunity, test the economics and start building the local
relationships needed to execute. An informed first step today can place
your business in a stronger position as the new system develops.
Planning a business investment in Brazil? Contact Meu
Contador Online to discuss your accounting, company-formation and
tax-modeling needs. Bring your proposed structure and
investment assumptions so the conversation can focus on practical next
steps and any legal, customs or immigration specialists your project may
require.
This guide provides general information as of the research date.
Transaction-specific advice should reflect the investor’s structure,
sector and applicable implementation rules.

Anderson Pavanello
Anderson Pavanello is the founder, partner, and board member of Meu Contador Online, a company that acquired more than 10,000 clients during its first five years of operation. He is also the Managing Partner of Meu Contador Prime and an investor in the capital markets and real estate. He holds a degree in Electrical Engineering with an emphasis in Telecommunications from FEI, a degree in Accounting from Estácio de Sá University, and an MBA in Strategic and Economic Business Management from Fundação Getulio Vargas (FGV). Anderson also served as an Executive Professor of Business Operations Management in FGV’s MBA program. Before entering the accounting industry as an entrepreneur, he spent more than a decade as an executive at Claro, leading integration projects involving Claro, NET, and Embratel, particularly in sales and customer service. He also worked in business process modeling and information systems development, including a platform that processed more than 20,000 prepaid plan activations per day. A father of three daughters, Anderson practices kung fu and is passionate about motorsports, regularly participating in track days. With a career spanning engineering, technology, accounting, management, and investments, he writes about the real challenges of doing business in Brazil, translating complex accounting, tax, and business topics into clear, practical, and useful insights for entrepreneurs.